Limited Seats
Running a business involves spending time and making countless decisions. As a business owner, you may be concerned with growing sales, reaching new customers, hiring more employees, and getting into different markets. In the case where your business revenue keeps rising and you are doing well financially, you may think that things are okay.
However, it is the other side of business operations that you may not give much thought to: figuring out the true meaning behind financial numbers.
It is possible that your business generates revenues and still cannot cover its expenses. It pays its GST on time but still gets an inquiry about the claimed Input Tax Credit. Its revenue increases annually, but a potential investor, reviewing its finances, realises that the company's financial situation is worse than it was expected to be.
These situations are not indicative of poor business or careless founders; sometimes, they occur due to the fact that some key financial information was not gathered in the process of doing business.
This blog will analyse three cases reflecting typical financial problems faced by different businesses. Note that these are just examples and are not accounts of any actual businesses.
More importantly, we will look at what could have been done differently—and how business owners can avoid making the same mistakes.
Imagine a startup that is making money by selling products directly to customers. The company’s revenue is going up, it launches new products, and the owner is exploring new markets. Everything seems to be okay looking at its income statement.
And then, one month, the company faces problems paying wages to employees and bills to suppliers on time.
The hidden factor: The business was making more profits, but the money got stuck
The owner of the company kept an eye on revenues and profits but did not pay much attention to cash flow.
The customers started paying more slowly, while the company kept buying more inventory for growth. Therefore, there was more money stuck in bills and inventory.
The company was profitable, but that does not always mean that the money is there.
What it cost:
Short-term borrowing during emergencies at unfavourable interest rates.
Difficulties with suppliers due to late payment.
Growth opportunity missed due to lack of cash.
What would have caught it early:
For example, preparing a monthly cash flow forecast could have assisted in spotting any expected shortages. A periodic review of receivables would have identified those customers who delayed payments.
Another way that the founder could have averted such risks was through reviewing inventory purchase plans and credit terms for clients.
Resolution:
After beginning to account for cash apart from profits, the firm became stricter on purchasing and examined customer terms of payment. In the two quarters that followed, the firm aimed at stabilising its cash situation.
Profit shows you if you are making money. Cash flow shows you if you can make your payments on time.
This is probably one of the most important lessons from the cash flow mistakes case study.
Want to know why your profit and bank balance don’t match? Read Profit vs. Cash: Why Your Bank Balance Never Matches Your P&L.
Consider an established SME that files its GST returns every month, on time. The owner assumes that means GST is under control.
Then a notice arrives from the department, questioning the Input Tax Credit (ITC) claimed in the returns.
The blind spot: Filing on time is not the same as filing correctly. Under GST law, ITC can be claimed only when specific conditions are met. One of them is that the supplier must have reported the invoice, so it appears in the business's GSTR-2B. Here, the business was claiming ITC based on its own purchase register, without reconciling it against GSTR-2B. Some suppliers had filed late or reported invoices incorrectly, and those gaps went unnoticed until the notice came.
What it cost:
Reversal of ITC found ineligible, with interest, and potentially penalty depending on the case
Weeks of management time spent tracing invoices, chasing suppliers and drafting the reply
Unplanned cash outflow and stress during what should have been routine compliance
A mismatch does not automatically make the entire credit invalid. The outcome depends on the facts, the documentation available and how the reply is handled.
What would have caught it early: A structured monthly GST ITC reconciliation process, before filing GSTR-3B:
Match the purchase register against GSTR-2B every month
Check eligibility of each credit under the applicable conditions
Follow up with suppliers on missing or mismatched invoices
Keep invoices and supporting documents organised and retrievable
Resolution: The business introduced a monthly reconciliation step before filing. Mismatches are now raised with suppliers within the same month, not discovered years later in a notice.
As this GST notice case study from India shows, compliance means more than meeting due dates. It means the numbers in your returns are verified, documented and defensible.
After a long time of establishing a good business, the founder engages in conversations with a possible investor/buyer. The revenues have been increasing, and the founder is hopeful that the business will fetch a good price.
However, during the balance sheet due diligence process, the buyer's team brings up some concerns about the financial standing of the business.
The founder was concentrated on the income statements and profitability without analysing the balance sheet on a regular basis.
In the long run, the owner's withdrawals and undocumented transactions with related parties have impacted the financial standing of the business. The founder was unaware of how much equity was being built up in the business.
A balance sheet indicates the assets, liabilities, and equity of the business at a particular period of time. Just because the profits are good does not mean that the cash or the equity of the business is increasing.
Through due diligence, it became clear that the founders' expectations were unrealistic given the financial position.
What it cost:
A lower value than what the founder hoped for.
Problems related to financial statements being analysed and rectified.
Questions posed by the buyer leading to lack of trust during the negotiations.
A poor balance sheet does not necessarily translate into a low business valuation. Nevertheless, inaccurate accounting records may lead to incorrect financial value and strength
What would have caught it early:
The founder could have prepared for an exit well before approaching potential buyers by:
Reviewing the balance sheet regularly.
Maintaining clear records of owner drawings.
Properly documenting related-party transactions.
Identifying inconsistencies before negotiations.
Obtaining a defensible business valuation based on relevant financial information.
Resolution:
After reviewing the accounts and organising the supporting documents, the founder provided a clearer financial picture to the buyer after going through the accounts and sorting out all the relevant documents. However, closing the deal was not an easy task due to the excessive work and stress that were involved in the process.
Preparation for meeting investors/buyers starts much earlier than one’s first discussion. Good financial records will assist you to better understand your own company.
The Pattern Across All Three
The above three cases highlight different issues like shortage of money, GST problems, and problems faced while doing an acquisition. However, there is one common problem among all three, which is that financial information was not being analysed properly.
Financial blind spot | What went wrong | What could have helped |
Cash flow | Money was tied up in receivables and inventory | Cash flow forecasts and receivables reviews |
GST compliance | ITC discrepancies went unnoticed | Timely reconciliation and compliance reviews |
Balance sheet | Financial records weren't properly understood before due diligence | Regular reviews and clear documentation |
This does not mean that all these cases have to be an indication of fraud or incompetence on part of anyone. In many instances, the business is expanding faster than the accounting procedures required to support it.
And the best thing about these skills is that they are learnable. They do not need you to be an accountant, but they do require you to know how to read your numbers, and what to ask them.
The actual costs involved were not only monetary but also included stress, loss of time, difficulties in building relationships, and lost opportunities because of delays in problem detection.
More financial visibility would have enabled each entrepreneur to recognise warning signs sooner.
There is no need to wait until a cash shortage occurs, a GST notification comes up, or your investors start asking questions for you to start learning about your company finances.
At Fintaxbusiness, we feel that there is no reason why financial literacy should be restricted to the accounts department alone. Business owners must also have knowledge of finances.
Our business finance workshop and masterclass will attempt to impart knowledge of financial concepts and the ability to interpret business reports and make better business decisions.
Financial literacy through monitoring of cash flow, checking of your GST, and understanding your balance sheets can prepare you for challenges ahead.
What are common financial blind spots in small businesses?
Failure to monitor cash flow, lack of GST reconciliation, and insufficient review of the balance sheet.
How can poor cash flow tracking lead to a cash crunch despite profits?
Late payments from clients, high levels of unsold inventory, and pending expenses can create a situation where there isn’t enough cash even though the business remains profitable.
What happens if ITC is claimed without GST reconciliation?
ITC that is not supported by GST reconciliation might cause discrepancies and possibly result in tax notices, credit reversals with applicable interest.
How does a weak balance sheet affect business valuation during an exit?
The balance sheet might raise questions about the business’s finances, especially incomplete information, unexplained transactions, and the level of liabilities.
How often should a business owner review cash flow, GST, and balance sheet numbers?
Cash flow needs to be monitored regularly, GST needs to be reconciled on time, and the balance sheet needs to be reviewed quarterly/monthly.
More insights to grow your business finance skills.
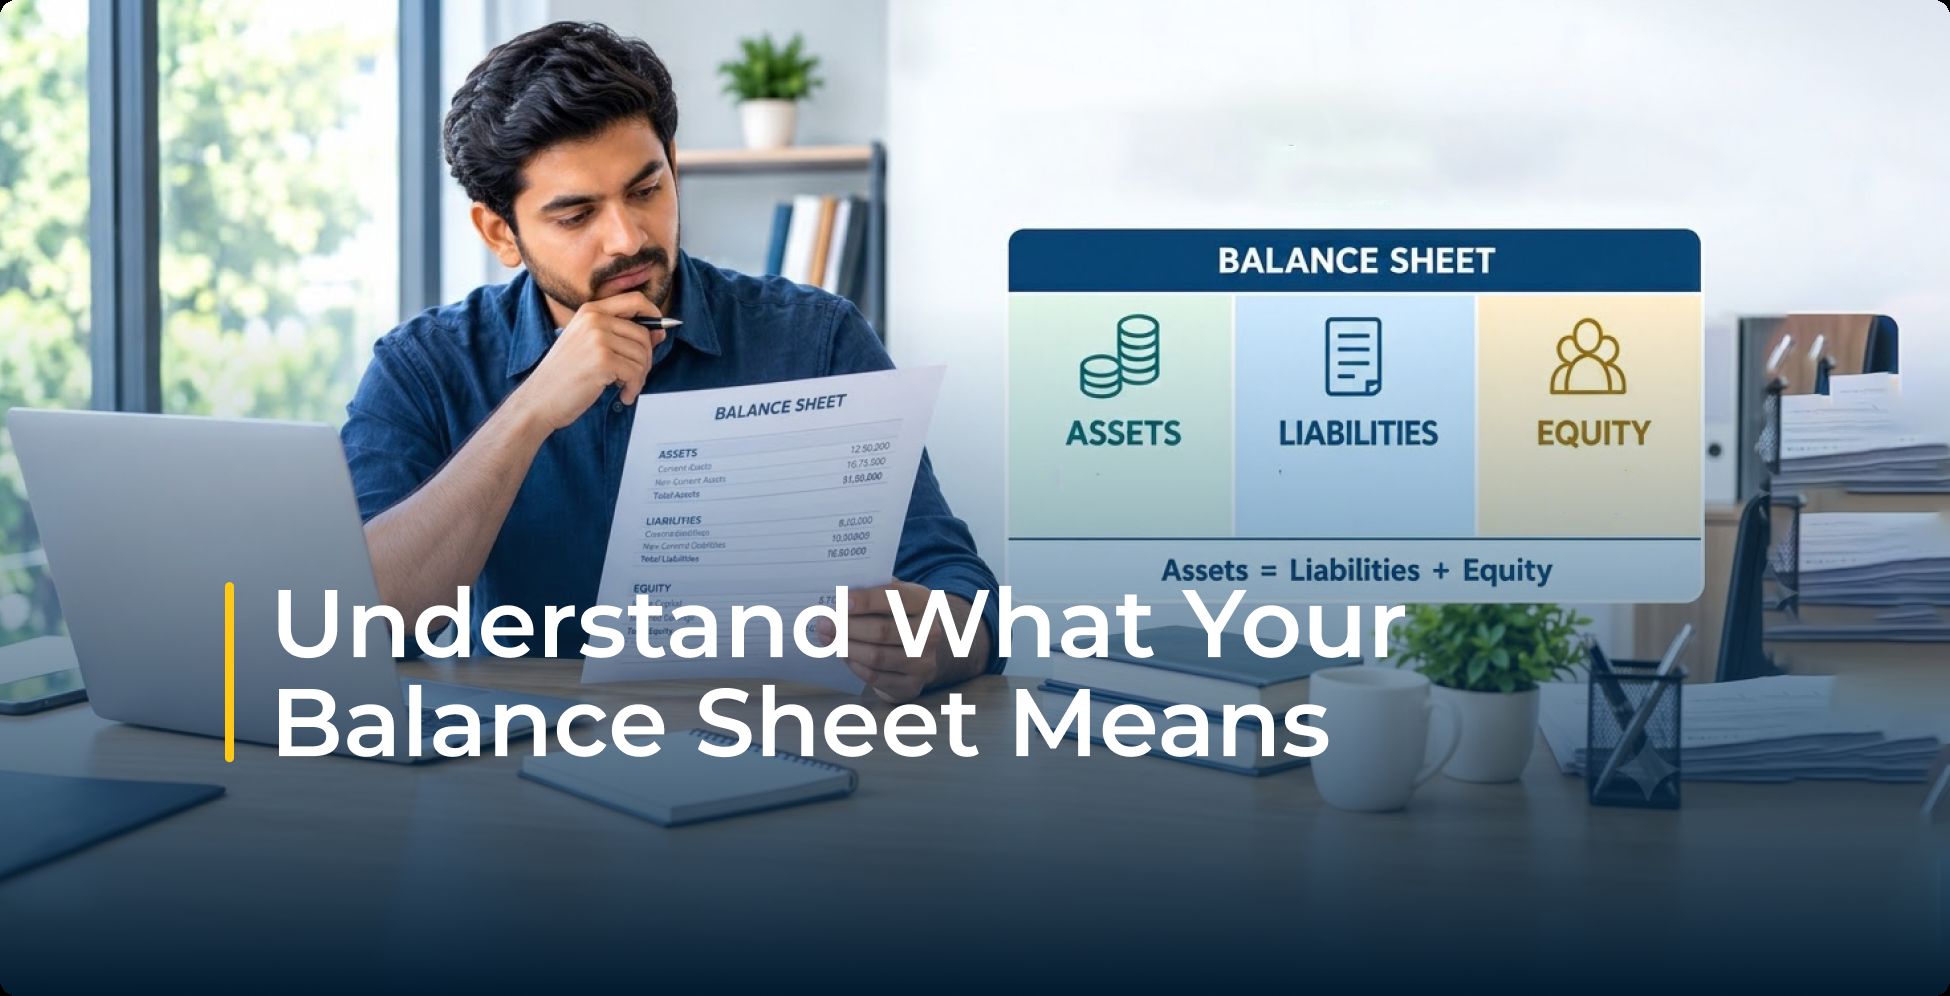
The majority of business owners consider their balance sheet as something that they need to give to their CA or financ...
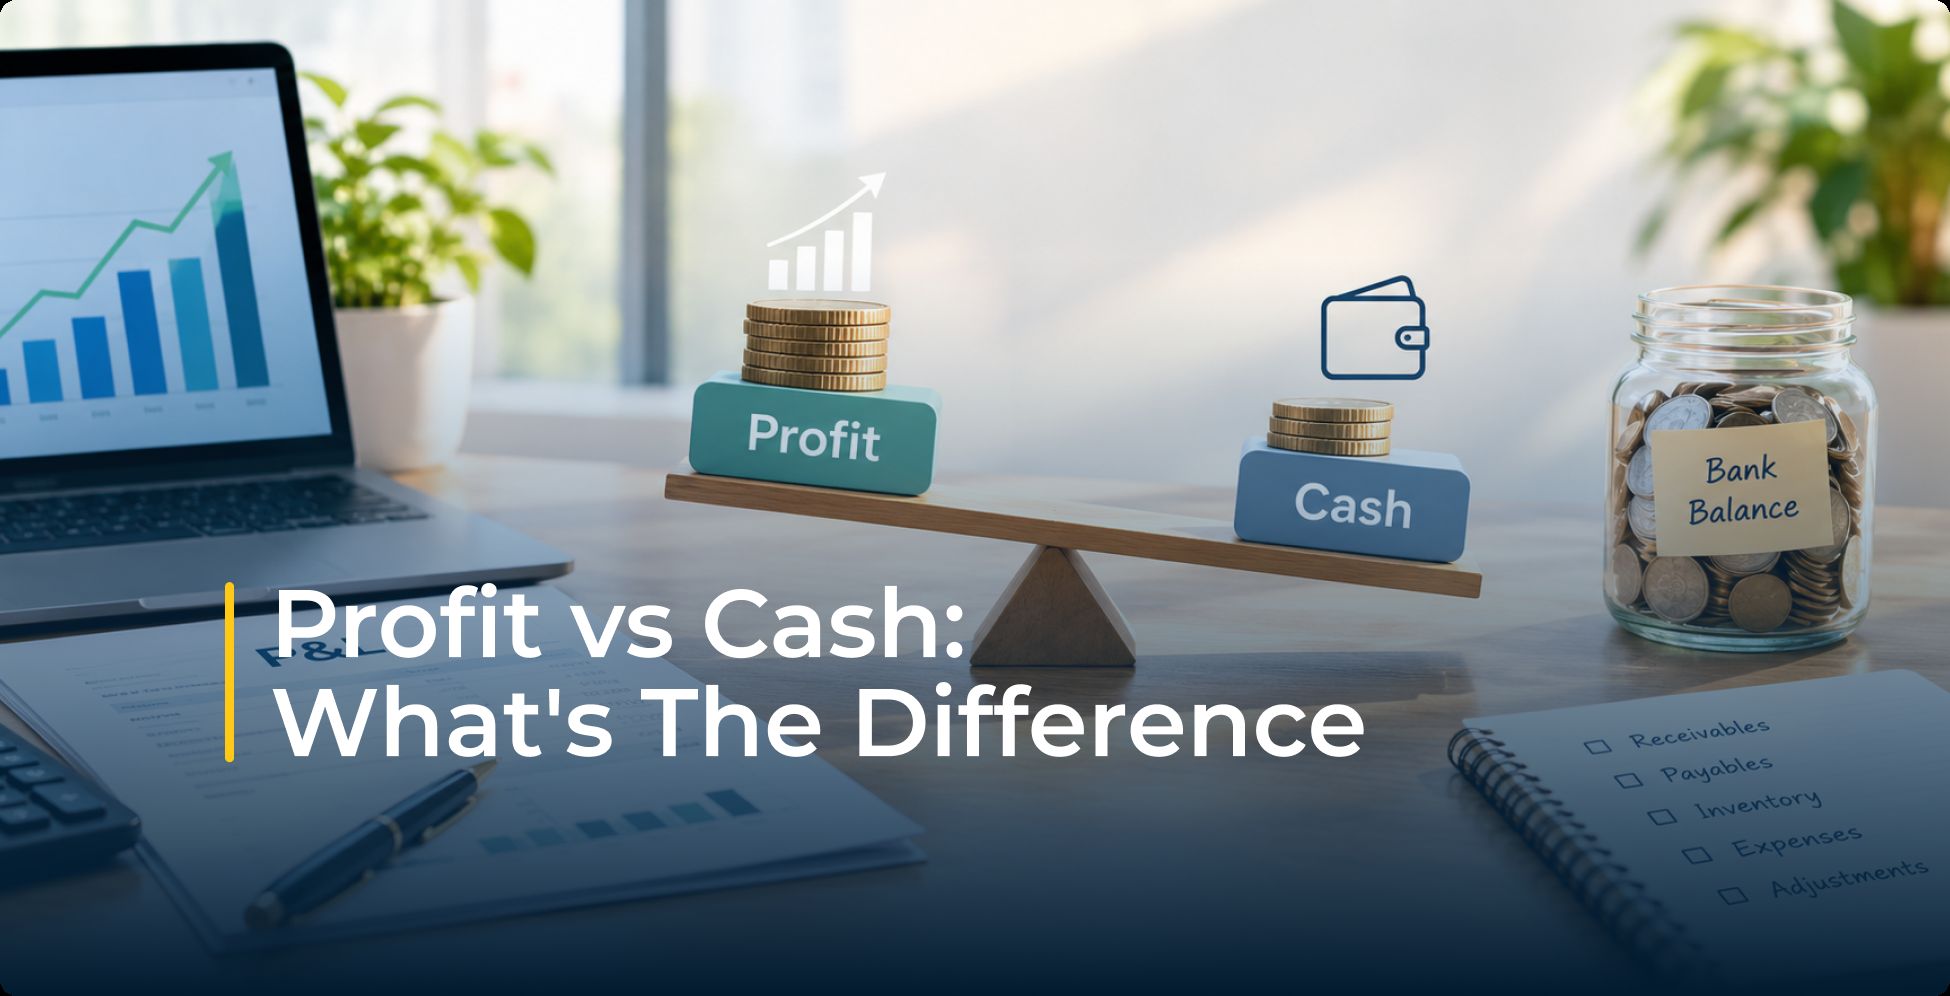
Your profit and loss statement indicates a profit of ₹8 lakhs for the last month. But your bank account balance shows ...
Let's start with a real example of the importance of financial literacy for business owners.