Limited Seats
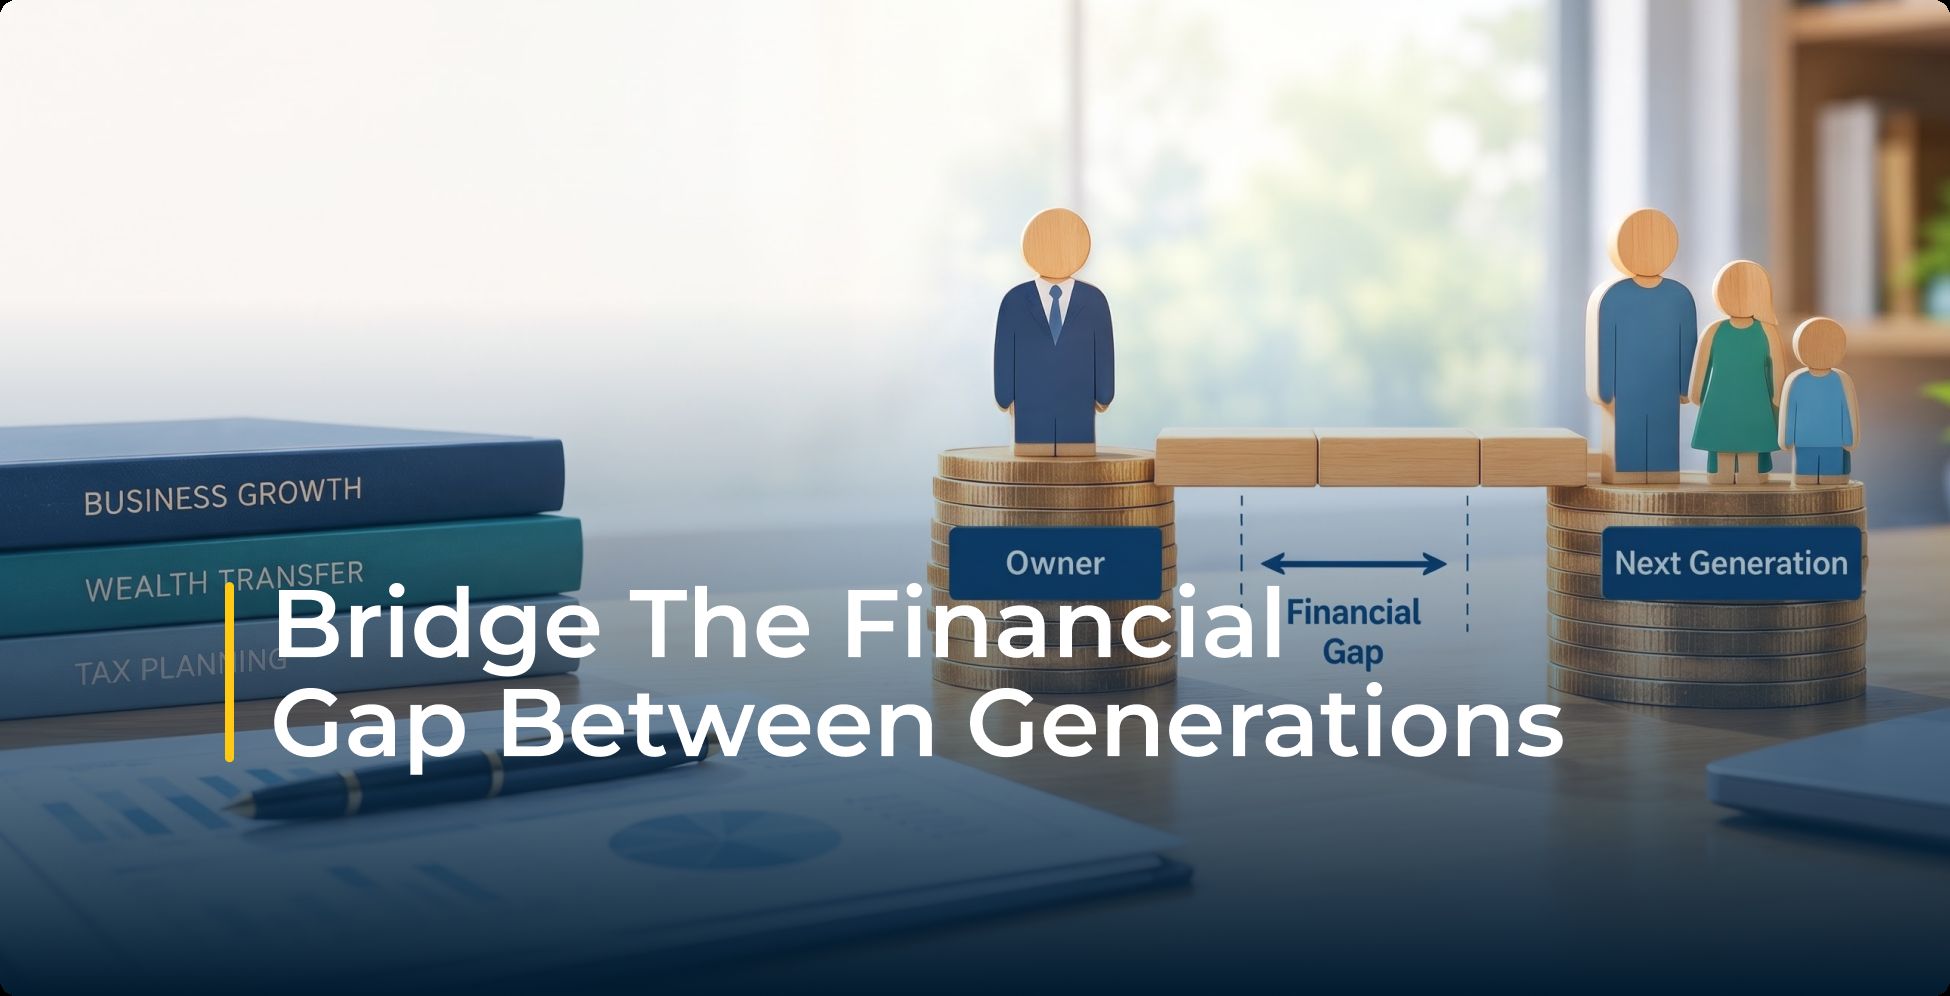
Anyone can start up a business, but only a few can keep it going for 20-30 years, then hand it to the next generation.
We see this happen all the time in most family businesses. The owner actively prepared his son / daughter by involving him in big sales meetings, marketing strategies, and daily business operations of the firm. When it is finally time to hand over the reins, the son / daughter is often left feeling completely overwhelmed and unready to make the big calls.
The problem wasn't a lack of effort or operational exposure; it was that the true foundation of leadership, the numbers, was never actually handed over. An effective business succession planning for a family business should bridge this financial gap.
To run the business successfully, the next generation has to truly understand the numbers from profit and cash flow to taxes, compliance, and funding. In this post, we’ll look at exactly where this financial knowledge gap comes from and how you can fix it long before the final handover happens.
Running a business involves years of experience, from team building to ensuring good quality of service to customers. It is through this experience that the entrepreneur knows what works best, what mistakes to avoid and also when to invest to grow the business.
Most family businesses operate successfully for several years under the leadership of the owner, but when the time comes for succession, they discover they have no well-tuned plan for transferring actual power. The successor has very little experience, but being familiar with operations is not equivalent to grasping what makes a business work.
Handing over the business isn't just about meeting the team or greeting customers, it's about passing on the financial knowledge, decision-making skills and business responsibilities.
In most cases, the next generation already understands the product, knows the major customers, and how products and services are delivered. The breakdown happens when they are confronted with financial reports: the Profit & Loss (P&L) statement, balance sheet, cash flow statement, and Management Information Systems (MIS) reports.
For example, an accountant may prepare a profit and loss statement showing ₹4 crore or ₹5 crore in profit. However, the business owner may look at the bank balance and wonder where that money has gone.
Understanding this difference requires knowledge of financial statements and cash flow. Without knowing how to read P&L and balance sheet metrics together, neither the owner nor the successor can explain where that cash went.
For a deeper breakdown, check out our guides:
Profit vs. Cash: Why Your Bank Balance Never Matches Your P&L
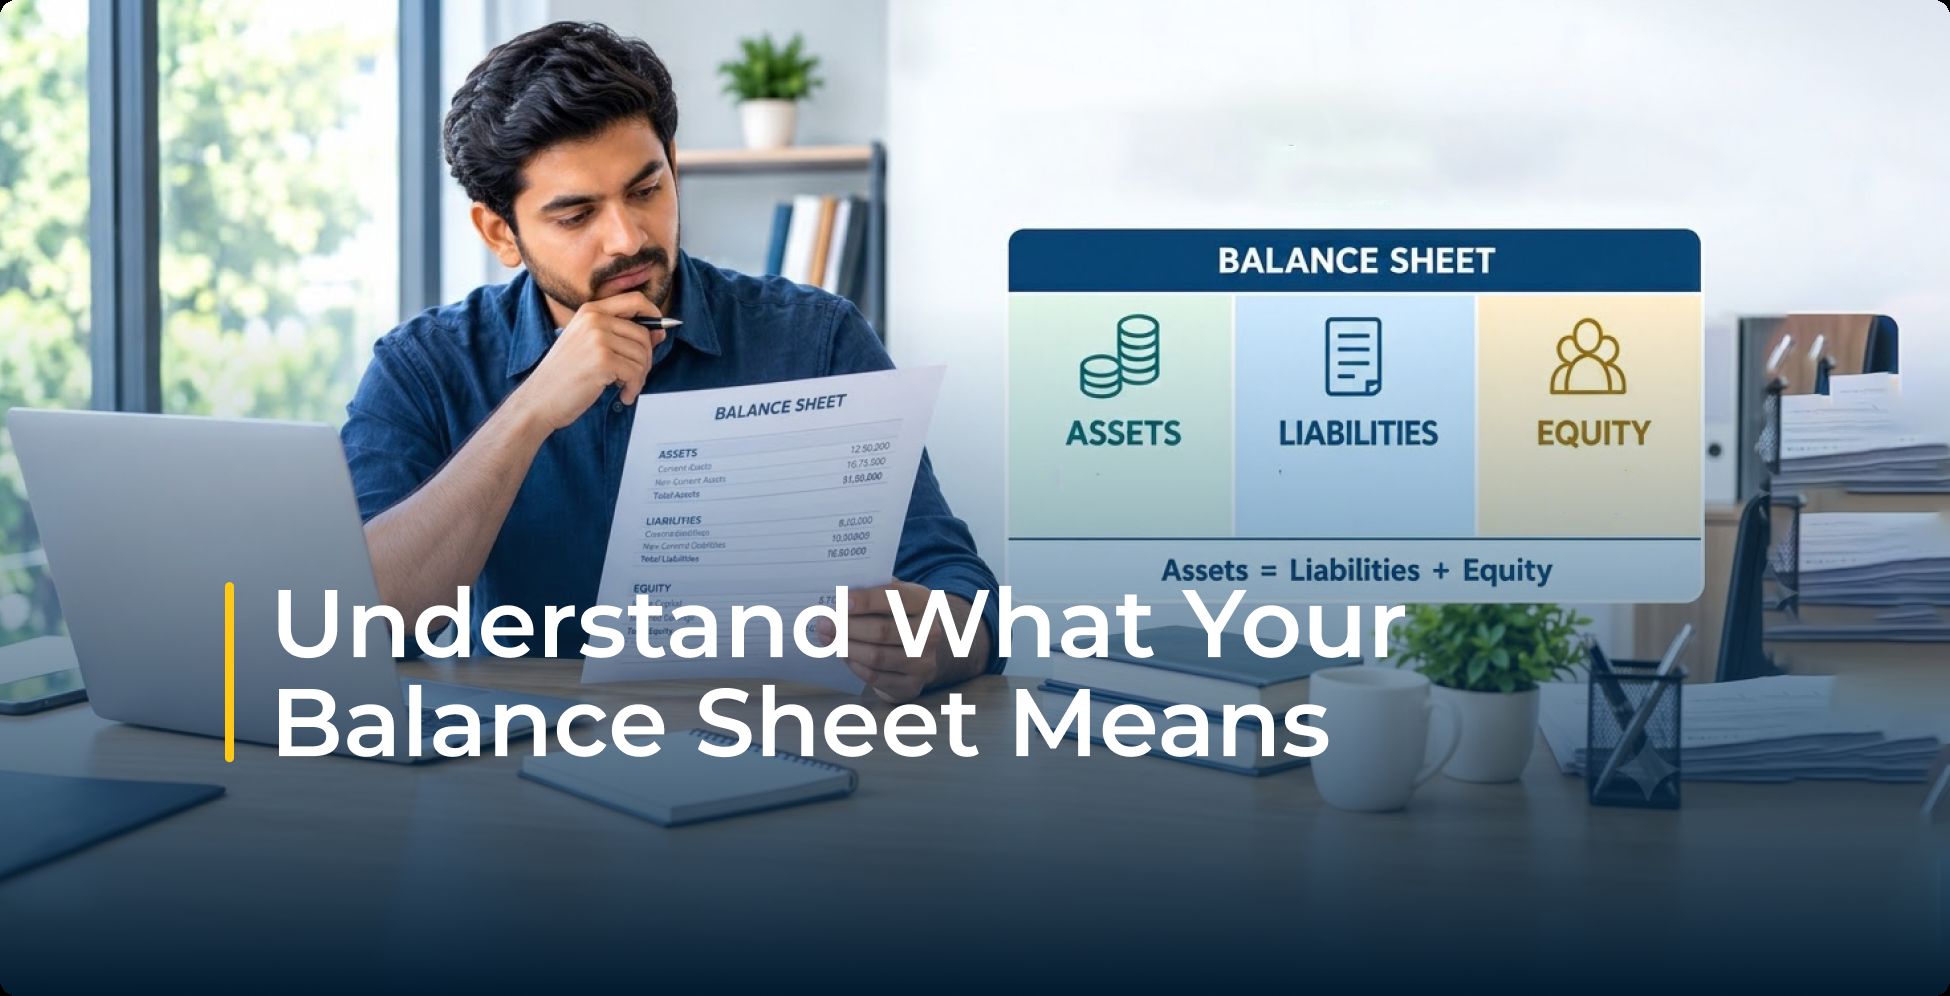
Balance Sheet Basics: What Your Numbers Are Actually Telling You.
A common misconception about business owners is that they think their advisors will make decisions for them, and take care of everything to do with finances. The truth is that each professional fills a certain, historical role:
The accountant records transactions.
The finance manager handles approvals.
The CA handles tax filings and compliance
The auditor reviews the year-end numbers.
These tasks enable the business to ensure accurate financial records and compliance. However, none of them can help in making such a decision as whether to launch a new product line, enter a new foreign market, or take a loan. That's the business owner's decision.
Taking over a family business means taking responsibility for decisions that can affect its financial stability and growth of the business.
Raising capital: Should the company pursue a bank loan or seek an equity investor? What valuation terms should be accepted, and what does equity dilution mean for long-term control?
Transactions: Understand GST and Income Tax Implications: How will GST and Income Tax affect profitability before entering or settling a major contract? Government authorities frequently review these structures during audits.
Global Expansion: Expanding across borders brings rules around the Foreign Exchange Management Act (FEMA), transfer pricing, and customs duties.
The exact requirements depend on the transaction and business structure. Understanding the potential implications before committing to an arrangement helps owners make better-informed decisions.
Want to learn more? Check out our YouTube video for the full breakdown.
As headcount expands, a business will fall under statutory regulation of the Wage Code, labor law, PF and ESI. Business owners leave these to "tomorrow" until regulatory authorities challenge the business or issue a compliance notice.
During a succession, these responsibilities also pass into the hands of the next generation. A successor who knows about sales and operations but nothing about compliance could well run into preventable difficulties, so it is important to address regulatory obligations in order to protect the legacy from unexpected disruption.
Many established owners admit to reviewing only two figures before signing year-end tax returns or audit reports: total profit and tax payable. They often execute major vendor and banking contracts without analyzing the financial commitments embedded in the terms.
To break this habit, incoming leaders should follow a structured review before signing any financial document:
Reconcile P&L with Cash Flow: Where was the generated profit allocated?
Review Outstanding Liabilities: Are GST, PF, and ESI obligations up to date?
Verify Asset Valuation: Are receivables and inventory accurately valued on the balance sheet?
Reviewing and understanding financial information is an important part of taking responsibility for a business.
A successful handover should begin at least twelve to eighteen months before the formal transition. Here are key steps to implement:
Monthly Financial Reviews: Require the next generation to review and analyze the monthly P&L, balance sheet, and cash flow statement.
Case-By-Case Strategy Walkthroughs: Walk successors through major historical decisions, explaining why loans were taken, why certain expansion plans were shelved, and how margins were protected.
Introduce them to the key customers and suppliers, along with the payment terms behind them.
Establish a Compliance Calendar: Create a centralized tracking system for GST, Income Tax, PF, ESI, and statutory filing deadlines.
Delegate Financial Authority Gradually: Transition banking and vendor authorization steps incrementally rather than all at once.
These steps help turn a handover from a one-time transfer into a structured learning process.
Financial clarity provides the confidence needed to lead, scale, and preserve a family legacy over decades. If you are preparing for a handover or stepping into a leadership role, building financial literacy is your most vital first step.
Take control of your business's financial future with the Fintaxbusiness Masterclass. Delivered over five days across 10 intensive sessions, this course uses real-world business case studies to cover compliance, capital raising, P&L, balance sheet analysis, cash flow management, GST, Income Tax, FEMA, transfer pricing, PF, ESI, and Wage Code applicability.
1. What financial skills should the next generation learn first?
The first priority is learning to read and reconcile the core financial statements: the Profit & Loss (P&L) statement, Balance Sheet, and Cash Flow statement. Understanding the difference between accounting profit and actual cash flow is essential.
2. Why doesn't profit in the P&L match the bank balance?
Profit reflects revenue earned minus expenses incurred during a specific period. It does not account for cash tied up in unpaid customer invoices (receivables), inventory, debt principal repayments, or capital expenditures, which directly affect the bank balance.
3. Is an accountant or CA enough to manage business finances?
Accountants and chartered accountants provide important accounting, tax and compliance support. However, business owners remain responsible for commercial decisions. They need to understand the financial information and professional advice used to evaluate those decisions.
4. When do PF, ESI and labour requirements apply to a business?
It depends on factors like the number of employees and the type of establishment. Business owners should verify current requirements with a qualified compliance professional rather than relying on a general threshold.
5. How early should a family business start succession planning?
Starting early gives the next generation time to understand financial statements, learn operational and compliance responsibilities, and gradually take part in important decisions.
More insights to grow your business finance skills.
Running a business involves spending time and making countless decisions. As a business owner, you may be concerned with growing sales, reaching ne...
The majority of business owners consider their balance sheet as something that they need to give to their CA or financ...
Your profit and loss statement indicates a profit of ₹8 lakhs for the last month. But your bank account balance shows ...